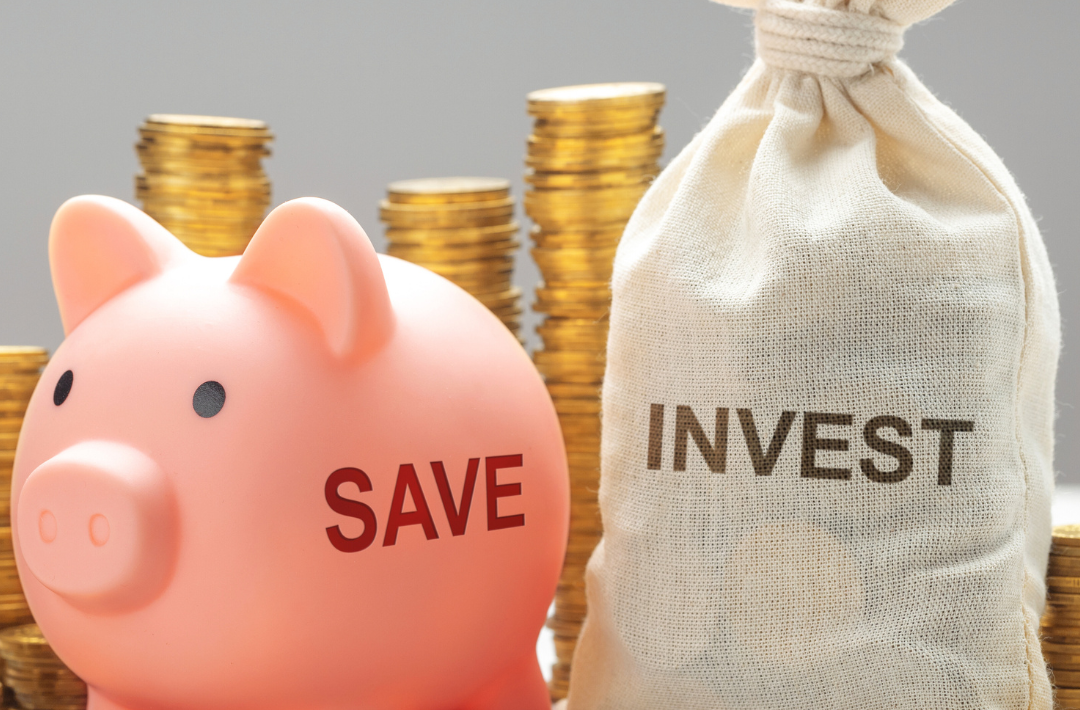
Choosing between saving and investing depends on the timeline and risk tolerance of your financial goals. Savings offers security and easy access, making it ideal for short-term needs or emergencies. Investing, on the other hand, involves more risk but can grow wealth over time.
The right choice hinges on whether the goal is immediate safety or long-term growth. Understanding this difference helps align financial decisions with personal priorities. This article will clarify when each strategy is most appropriate and why both can play important roles.
Key Differences Between Saving and Investing
Saving and investing serve distinct roles in financial planning. They differ primarily in purpose, the level of risk involved, expected returns, and how easily funds can be accessed when needed.
Purpose and Goals
Saving focuses on preserving money for short-term needs or emergencies. It is ideal for building an emergency fund, making small purchases, or setting aside cash for upcoming expenses. Typically, saving is done through a bank account or other low-risk financial institution products that prioritize safety over growth.
Investing targets long-term financial goals such as retirement, buying a home, or funding education. It involves committing money to an investment account or brokerage account, where funds are allocated to stocks, bonds, or other assets with the potential to grow over time. The goal is to increase wealth, often accepting fluctuations in value.
Risk and Returns
Saving carries very low risk since funds are usually held in insured bank accounts or similarly secure places. The returns, often in the form of interest, are minimal but predictable. This makes saving a safer choice for those averse to loss in principal.
Investing exposes money to market risk, meaning the value can rise or fall. The returns vary widely depending on asset types and market performance, but generally offer higher potential growth than savings. This risk-return tradeoff is crucial for financial goals requiring more accumulation over time.
Liquidity and Access
Saving provides high liquidity, meaning money is easily and quickly accessible without penalties or significant delays. Funds in checking or savings accounts can be withdrawn or transferred instantly, supporting immediate or unexpected expenses.
Investing usually involves lower liquidity. Selling investments often takes time and may incur fees or tax consequences. Some investments have restrictions on when funds can be accessed without penalty. Understanding liquidity needs is vital to choosing the right balance between saving and investing.
When to Choose Saving vs. Investing
Deciding between saving and investing depends primarily on time horizon, financial goals, and how much risk one is willing to accept. It’s essential to balance the need for immediate funds with the desire for long-term growth.
Time Horizon Considerations
The length of time before funds are needed influences the choice between saving and investing. For goals within a few months to a few years, saving is preferable because it preserves purchasing power and limits exposure to market fluctuations.
If the goal is a decade or more away, investing becomes more suitable. Investments like stocks and bonds typically offer higher returns over time, helping to beat inflation. This growth potential is critical for long-term goals such as retirement or a college fund.
Short-Term Goals and Emergency Savings
Short-term goals require liquidity and safety. Holding cash in savings accounts or money market funds serves as a reliable emergency fund or cash cushion. This ensures quick access to money without risk of loss.
Emergency savings should cover 3-6 months of living expenses to handle unforeseen costs like medical bills or car repairs. Investing these funds could lead to losses in a market downturn, which is risky when cash is needed immediately.
Long-Term Goals and Wealth Growth
Investing is generally the better option for long-term goals, as it offers the chance to grow wealth beyond inflation. Stocks, bonds, and mutual funds carry risks but historically outperform savings accounts over decades.
A financial plan focused on retirement or wealth accumulation uses investing to maximize returns. Diversification across asset classes helps manage risk, and regular contributions leverage compound interest for substantial growth.
Assessing Your Risk Tolerance
Risk tolerance determines comfort with potential loss. Those with low risk tolerance might prioritize saving, favoring security over high returns. Investing involves market fluctuations, and not everyone can handle the stress of volatility.
Financial advisors often recommend a mix based on individual risk profiles. Younger individuals with higher risk tolerance can allocate more to investments, while those nearing goals might shift toward safer savings to protect capital.
Exploring Saving and Investing Vehicles
Saving and investing involve different tools tailored to distinct financial goals. Savings options typically prioritize safety and liquidity, while investment vehicles aim for growth with varying levels of risk and diversification.
Types of Savings Accounts and Options
Savings accounts provide easy access to funds and generally earn modest interest. Traditional savings accounts at banks or credit unions are insured by the FDIC or NCUA up to set limits, which protects the depositor’s money.
High-yield savings accounts, often available through online banks, offer higher annual percentage yields (APY) than standard accounts, making them attractive for emergency funds or short-term goals.
Money market accounts combine checking features with variable interest rates, usually higher than regular savings, and are also insured.
Certificates of deposit (CDs) lock in money for fixed terms at a guaranteed rate, typically providing better returns than savings accounts but with penalties for early withdrawal.
Overview of Investment Vehicles
Investment vehicles include brokerage accounts, which allow the purchase of assets like stocks, bonds, mutual funds, and exchange-traded funds (ETFs). These options carry more risk but offer potential for higher returns.
Index funds and ETFs offer diversified exposure to broad market segments with lower fees, suitable for building a diversified portfolio across various asset classes like equities and fixed income.
Real estate investment is another avenue, often less liquid and requiring more capital, but it diversifies portfolios beyond the stock market.
Each vehicle suits different time horizons and risk tolerance, making it essential to align choices with personal financial goals.
Practical Strategies and Considerations
Effective money management requires clear choices about when to save and when to invest. It also involves understanding costs and knowing when professional guidance can improve outcomes.
Balancing Saving and Investing for Your Goals
He should prioritize saving in a checking account or other liquid accounts for short-term needs like emergency funds or upcoming expenses such as a down payment. For medium- to long-term goals like retirement, investing in retirement accounts such as a 401(k) or IRA is generally better due to higher return potential.
Paying off high-interest debt, such as credit card balances or student loans, may take precedence over investing because of the guaranteed savings on interest. Contributions to low-cost index funds within retirement accounts can boost retirement savings while minimizing risks and fees.
Managing Fees and Costs
Fees directly reduce investment returns, so minimizing them is essential. Platforms like Charles Schwab and Fidelity offer free trades and low-cost index funds, which help keep expenses down.
He should compare expense ratios when choosing funds and consider account maintenance fees. Some retirement accounts or brokerage accounts might charge inactivity or service fees. Regularly reviewing these costs ensures more money stays invested or saved.
Working With Financial Advisors
Financial advisors can provide tailored strategies for saving, investing, and managing debt, especially for complex situations. It is important to understand different advisor fee structures—some charge a percentage of assets under management, while others use flat fees or hourly rates.
Choosing a fiduciary advisor ensures recommendations prioritize the client’s best interests. A knowledgeable advisor can help optimize contributions to retirement accounts, balance investment risk, and address goals like paying off high-interest debt before investing.
